Westminster Point Investment Return: Conservative Base Case
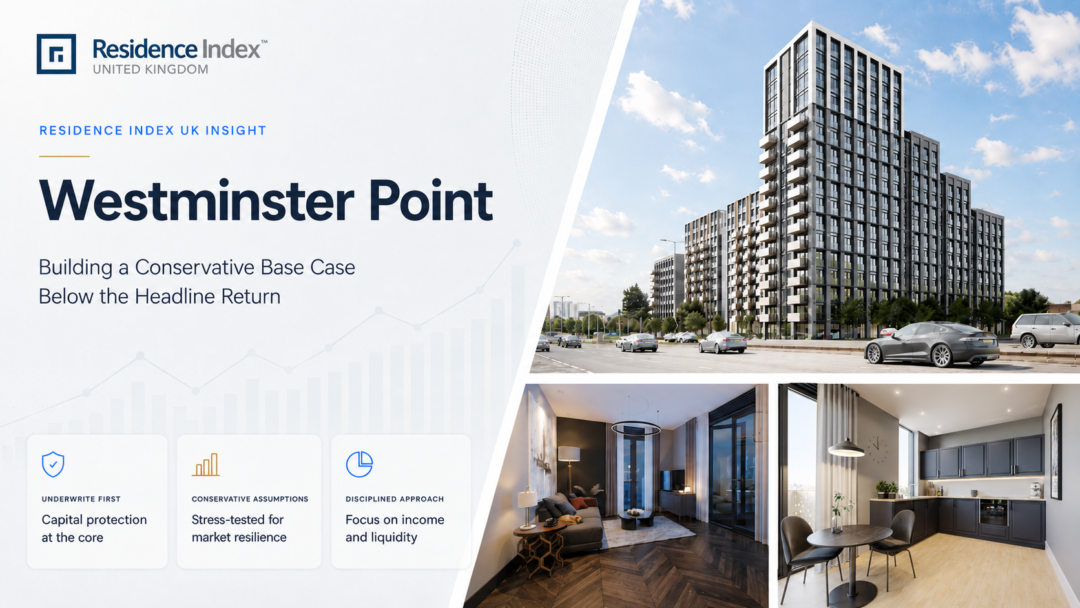
Westminster Point: Building a Conservative Base Case Below the Headline Return
A strong property investment should not require the most optimistic scenario to occur.
That principle matters when analysing the Westminster Point investment return.
Westminster Point in Liverpool is currently marketed from £170,000, with a 10% deposit plus a £5,000 reservation payment and the balance due on completion. The development is scheduled for Q2 2027, has a 999-year lease and is marketed as short-term-let approved, with circa 10–12% net returns referenced for that strategy.
Those headline figures deserve attention.
However, they should not become the only figures inside an investor’s spreadsheet.
A more useful question is:
What happens if the actual Westminster Point investment return is materially lower than the headline projection?
If the property still performs the role you need it to perform, the investment case becomes considerably stronger.
Start Below the Headline Westminster Point Investment Return
Marketing projections are useful starting points.
They are not guarantees.
Short-term rental performance can be influenced by:
- occupancy;
- nightly rates;
- seasonality;
- management costs;
- utilities;
- cleaning;
- maintenance;
- service charges;
- platform or booking costs;
- furnishing replacement;
- insurance; and
- periods where demand is weaker than expected.
Therefore, rather than underwriting Westminster Point at 10–12% from day one, an investor could deliberately build a lower base case.
This is similar to the principle explored in Why Yield Is the Most Misunderstood Metric in UK Property Investment: one percentage alone rarely tells you whether a property is genuinely attractive.
The objective is not to argue that Westminster Point cannot achieve its marketed return.
It is to make sure your investment decision does not depend on it.
What Does a Lower Return Look Like at £170,000?
Using the current starting price of £170,000, the following table shows the annual net income equivalent of different return assumptions.
Return Assumption | Annual Income Equivalent | Monthly Equivalent |
12% | £20,400 | £1,700 |
10% | £17,000 | £1,417 |
8% | £13,600 | £1,133 |
7% | £11,900 | £992 |
6% | £10,200 | £850 |
These figures are not rental forecasts.
They simply show what different percentage returns mean when applied to a £170,000 purchase price.
That distinction matters.
Instead of asking whether 10–12% sounds attractive, you can ask:
Would Westminster Point still fit my strategy if the eventual return were closer to 7–8%?
If the answer is yes, the investment has more room for error.
If the answer is no, you may be relying too heavily on the optimistic case.
A Conservative Base Case Could Be 7–8%, Not 10–12%
One practical approach would be to treat the marketed 10–12% return as an upside case rather than your base assumption.
For example:
Upside case: 10–12%
Base case: 7–8%
Stress case: 6%
The exact percentages an investor chooses will depend on their objectives and the evidence available.
However, the principle is valuable.
A conservative base case deliberately leaves space for something to go wrong.
Perhaps occupancy is lower.
Perhaps nightly rates need to be reduced during quieter periods.
Perhaps management costs increase.
Perhaps furnishing requires replacement sooner than expected.
Perhaps the service charge rises.
You do not need to predict which assumption will disappoint.
You need enough margin in the numbers to absorb disappointment somewhere.
Do Not Confuse the Base Case With a Forecast
A conservative base case is not necessarily your prediction of what will happen.
It is an underwriting tool.
Suppose independent evidence eventually suggests the property could realistically generate a strong short-term-let income.
That is positive.
However, an investor might still choose to model only 75% or 80% of that expected performance when making the purchase decision.
The remaining amount becomes potential upside.
This is far safer than needing every optimistic assumption to be correct just to achieve an acceptable result.
Our guide to How to Stress-Test a Property Against Three Interest-Rate Scenarios applies the same philosophy to borrowing costs: the investment should ideally remain manageable when conditions become less favourable.
Use Liverpool Rental Data as a Reality Check
Short-term lets and conventional long-term rentals are different markets.
Therefore, Liverpool’s standard rental data should not be used as a direct prediction of what Westminster Point will earn.
It can, however, provide useful context.
According to the latest Office for National Statistics Liverpool housing data, the average private rent across Liverpool reached £909 per month in July 2026, up 5.7% from £860 one year earlier.
The same data shows average July 2026 rents of approximately:
- £683 for one-bedroom homes;
- £834 for two-bedroom homes; and
- £783 for flats and maisonettes overall.
Liverpool’s average house price was £185,000 in June 2026, while the average flat or maisonette price was £128,000.
These citywide averages include many properties that are not comparable with Westminster Point.
Nevertheless, they are useful because they prevent investors from viewing a development entirely in isolation.
A good underwriting file should contain both:
Development-specific projections
and
Independent local-market evidence.
Compare Like With Like
Average Liverpool rent should not become the only benchmark either.
Westminster Point’s actual rental performance will depend on the quality, specification, unit type, exact location, management model and tenant or guest experience.
That means investors should build a more focused comparable set.
Look for apartments with similar:
- bedroom count;
- floor area;
- specification;
- location;
- parking availability;
- furnishing;
- building quality;
- transport access; and
- short-term-let suitability.
Our article on tracking rent per square foot rather than monthly rent alone explains why normalising rental evidence can reveal differences that headline monthly rents hide.
A £1,400 monthly rent means much more when you know what size and quality of apartment produced it.
Build the Return From the Bottom Up
A conservative Westminster Point investment return should ideally be calculated from income and costs rather than simply reducing the advertised percentage.
For a short-term-let strategy, your model might include:
Income
Estimated average nightly rate
× realistic occupied nights
= gross booking income
Then subtract:
Management
Short-term-let management can be materially more intensive than conventional letting.
Model the actual proposed management fee rather than assuming it will be negligible.
Utilities
Unlike many standard tenancies, short-term-let owners may carry electricity, heating, water and broadband costs.
Cleaning and Linen
Check who pays, how frequently cleaning occurs and whether the cost is recovered from guests.
Service Charge
Apartment developments carry communal operating costs.
Ask for the latest estimate and stress-test future increases.
Maintenance
Allow for repairs inside the apartment as well as replacement of furniture, appliances and smaller items.
Insurance
Confirm what is covered through the building and what remains the owner’s responsibility.
Voids and Seasonality
Do not assume identical occupancy every month.
A conservative model should account for quieter periods.
Only after these costs are included should the resulting return be described as genuinely meaningful to the investor.
Separate Property Return From Financing Return
Another important distinction is leverage.
The property’s operating return and your return on cash invested are not the same thing.
Mortgage finance can increase returns on equity when the property performs well.
It can also increase sensitivity to:
- interest rates;
- mortgage fees;
- refinancing conditions;
- valuations; and
- loan-to-value restrictions.
Therefore, calculate Westminster Point in two stages.
First:
How does the property itself perform before finance?
Then:
What happens to my personal cash flow after mortgage costs?
This makes it much easier to see whether the underlying property is strong or whether leverage is doing most of the work.
Include Purchase Taxes and Acquisition Costs
The purchase price is not always the complete cost of entering an investment.
Investors should allow separately for legal fees, financing costs, furnishing where applicable and taxes.
Current GOV.UK Stamp Duty Land Tax guidance shows that the amount payable depends on factors including the purchase price, whether the buyer already owns residential property and whether the buyer is treated as UK resident for SDLT purposes.
Additional residential properties usually attract rates five percentage points above the standard residential rates.
Tax circumstances vary substantially.
Therefore, investors should obtain individual tax advice rather than inserting somebody else’s SDLT calculation into their own investment model.
Ask What Happens at 80% Occupancy Rather Than 100%
Short-term-let calculations can become surprisingly sensitive to occupancy.
Imagine the property performs strongly during weekends, events and peak visitor periods.
That still does not mean every available night will be sold.
Instead of working backwards from maximum potential revenue, calculate several occupancy scenarios.
For example:
Strong case: higher occupancy and stronger nightly rate
Base case: normalised occupancy and moderate nightly rate
Stress case: lower occupancy with no increase in nightly rate
The exact percentages should come from credible comparable evidence.
The important part is avoiding a model where the investment requires unusually high occupancy throughout the year.
Treat Rental Growth as Upside
Liverpool rents have recently been rising.
The ONS recorded annual Liverpool rental growth of 5.7% to July 2026.
That is encouraging context.
However, today’s investment should not depend on several years of similar growth.
A conservative model can begin with realistic present-day rental evidence.
Then ask:
What does the investment look like with no rental growth for two years?
If future rental growth occurs, it strengthens the result.
If the deal only becomes attractive after assuming rents rise significantly, the base case may be too optimistic.
Build an Evidence File Before Reserving
A spreadsheet is only as strong as the evidence behind each input.
Before paying a reservation fee, record where every important assumption came from.
Residence Index UK’s guide to building a property investment evidence file before reserving recommends separating verified information from assumptions and saving the documents that support the investment case.
For Westminster Point, that evidence file could contain:
- the current price list;
- reservation agreement;
- payment schedule;
- lease information;
- service-charge estimate;
- short-term-let permissions;
- management agreement;
- projected occupancy;
- nightly-rate evidence;
- local long-let comparables;
- nearby short-let comparables;
- floor plans;
- developer information;
- completion timetable; and
- exit-market evidence.
Label each number clearly:
Verified
Assumed
or
Still to confirm
That simple discipline can prevent projections from gradually becoming treated as facts.
Consider the Exit as Well as the Income
A property producing good rental income still needs a future buyer.
Potential purchasers of Westminster Point could include other investors, owner-occupiers or buyers seeking a Liverpool base.
Therefore, the investment case should not focus entirely on short-term rental income.
Ask:
Would the apartment remain attractive if short-term-let economics weakened?
Would a conventional tenant want to live there?
Would another investor buy it based on long-term rental income?
Would an owner-occupier value the unit?
A wider pool of potential users and buyers generally gives investors more strategic flexibility.
Headline Returns Should Be the Bonus, Not the Requirement
The most useful way to interpret Westminster Point’s marketed 10–12% net return is not:
“I will receive 10–12%.”
A better interpretation is:
“The short-term-let strategy is being marketed with the potential for strong returns. What happens if I underwrite materially less?”
At a starting price of £170,000, modelling a 7–8% base case would represent annual income equivalent to approximately £11,900–£13,600.
If independent evidence supports something higher, excellent.
But the investment decision should ideally remain defensible without needing the top of the range.
That creates a margin of safety.
The Residence Index UK View
Westminster Point has several characteristics that make it worth analysing: a comparatively accessible Liverpool entry price, a long lease, staged payment terms and the ability to consider a short-term-let strategy.
However, the strongest investment case is not created by repeating the headline return.
It is created by challenging it.
Start lower.
Stress the occupancy.
Stress the nightly rate.
Allow realistic operating costs.
Test conventional rental demand.
Include financing separately.
Then decide whether the remaining return still fits the role the property needs to perform inside your portfolio.
That is how a marketing projection becomes an investment decision.
For further opportunities, compare current Residence Index UK properties or explore the latest Residence Index UK investment insights before committing capital.
Important: Property investment involves risk. Rental and capital-growth projections are not guaranteed. Tax, legal and mortgage circumstances vary between investors, so appropriate independent professional advice should be obtained before purchase.