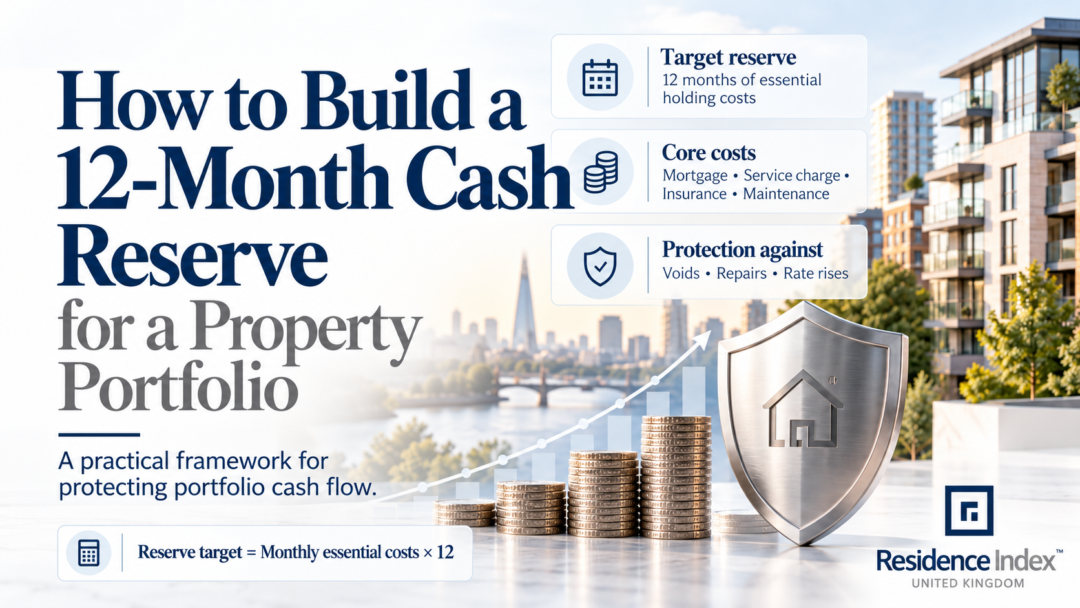
How to Build a 12-Month Cash Reserve for a Property Portfolio
How to Build a 12-Month Cash Reserve for a Property Portfolio
Property investors spend a great deal of time thinking about capital.
The deposit.
Stamp duty.
Legal fees.
Furniture.
Mortgage costs.
The next acquisition.
But one form of capital often receives much less attention:
cash that is deliberately not invested.
A property portfolio can look strong on paper while remaining financially fragile if almost every available pound is tied up in deposits, equity or property.
A repair arrives.
A tenant leaves.
A mortgage payment increases.
A service charge changes.
Several costs fall in the same month.
Suddenly, an investor with substantial property wealth can find themselves short of accessible cash.
That is why building a 12-month property cash reserve can be one of the most useful steps in making a portfolio more resilient.
The objective is not to leave an arbitrary amount sitting in a bank account.
It is to understand what your portfolio costs to hold — and build enough liquidity to absorb a difficult period without being forced into a poor decision.
What Does a 12-Month Property Cash Reserve Actually Mean?
It does not necessarily mean saving 12 months of gross rental income.
Suppose a portfolio generates £8,000 per month in rent.
That does not automatically mean the investor requires:
£8,000 × 12 = £96,000
Instead, calculate the expenses that would continue even if some rental income disappeared.
These could include:
- Mortgage payments
- Service charges
- Ground rent where applicable
- Insurance
- Management costs
- Compliance expenditure
- Essential maintenance
- Utilities paid by the landlord
- Accounting and administration
- A realistic allowance for repairs and void periods
The reserve should be based on the financial obligations of holding the portfolio, not simply its headline income.
This distinction matters because cash reserves are about survival capacity.
The question is:
How much cash would I need to keep the portfolio functioning if conditions became temporarily worse?
Start With Your Non-Negotiable Monthly Costs
Begin with costs that cannot simply be stopped because rental income has fallen.
Imagine an investor owns three properties.
Their monthly portfolio obligations might look broadly like this:
Mortgage payments: £3,600
Service charges and ground rent: £500
Insurance: £150
Management and administration: £300
Average maintenance provision: £375
Compliance and other costs: £125
Total:
£5,050 per month
A straightforward 12-month target would therefore be:
£5,050 × 12 = £60,600
This is an illustration rather than a universal recommendation.
Another investor with unencumbered property and low running costs might need substantially less.
An investor with significant leverage, premium apartment service charges or several properties refinancing within a short period might want considerably more.
The point is to calculate your own number.
Do Not Assume Every Property Needs the Same Reserve
A portfolio reserve becomes more useful when calculated property by property.
One apartment may have:
- predictable management;
- a long-standing tenant;
- low maintenance;
- modest service charges; and
- a long fixed-rate mortgage.
Another may have:
- a tenancy ending shortly;
- higher service charges;
- older appliances;
- refinancing approaching;
- planned refurbishment; and
- greater exposure to unexpected expenditure.
Those properties do not represent identical liquidity risks.
Create a simple reserve figure for each asset.
Then combine them into a portfolio-level target.
This is similar to the principle behind a property interest-rate stress test: risk becomes easier to manage when you stop treating the portfolio as one headline number and start examining what happens under less comfortable assumptions.
Separate Normal Expenses From Emergencies
One common mistake is calling money a reserve when it is already committed.
Suppose you have £20,000 in your property account.
That sounds reassuring.
But perhaps:
£5,000 is required for tax.
£3,000 will pay an upcoming service charge.
£2,000 is allocated to furniture replacement.
£4,000 will cover planned refurbishment.
Your genuinely available reserve is not £20,000.
It is closer to £6,000.
This is why it can help to separate cash into different categories:
Operating cash
Money used for normal monthly expenditure.
Tax provision
Money expected to be required for tax liabilities.
Planned expenditure
Known refurbishment, furnishing or capital expenditure.
Emergency portfolio reserve
Cash available when something unexpected happens.
These amounts can sit within the same financial structure, but investors should know which money is genuinely uncommitted.
Build the Reserve Around the Events That Could Hurt You
A reserve becomes more meaningful when connected to actual risks.
Consider what could realistically happen across your portfolio.
A Longer-Than-Expected Void
Even strong rental properties can become vacant.
Perhaps a tenant leaves during a slower period.
Perhaps refurbishment takes longer than expected.
Perhaps the asking rent needs adjusting.
The important question is not whether a void will definitely happen.
It is whether the portfolio remains comfortable if it does.
An Unexpected Repair
Boilers, appliances, plumbing, electrics and internal finishes eventually require attention.
Landlords also retain important property safety and maintenance responsibilities. The official GOV.UK landlord responsibilities guidance provides a useful reference point for owners in England.
A cash reserve allows essential work to be dealt with because it needs doing — rather than because there happens to be enough money in that month’s rental account.
Higher Mortgage Costs
Refinancing can materially alter portfolio cash flow.
A property comfortably producing surplus cash at one mortgage rate may look very different at a higher rate.
That is why the reserve calculation should sit alongside your interest-rate stress testing rather than separately from it.
Ask what your monthly holding cost becomes under a less favourable finance scenario.
Then consider building the reserve against that figure.
Service-Charge Increases
Apartment investors should give service charges particular attention.
Residence Index UK’s guide to reading a service-charge budget before you buy explains why investors should examine what the charge funds, previous changes and whether the building has appropriate reserve provisions.
Your own personal cash reserve is separate from the building’s reserve or sinking fund.
The building may have money allocated towards communal works.
You still need liquidity for your own obligations.
Several Problems at Once
This is the scenario that really tests a portfolio.
One property becoming vacant may be manageable.
One large repair may be manageable.
A mortgage refinance may be manageable.
But imagine:
One property is vacant.
Another needs a £3,000 repair.
Two mortgages refinance at higher rates.
A service-charge invoice arrives.
That is when cash reserves demonstrate their value.
Investment risk rarely arrives conveniently one expense at a time.
Build the Reserve Gradually
An investor does not necessarily need to produce the entire 12-month reserve immediately.
Building it systematically can be more practical.
For example, an investor could decide that a percentage of monthly portfolio surplus automatically stays in the reserve account.
Suppose the portfolio produces £3,000 per month after normal expenditure.
Instead of treating the entire £3,000 as available personal income or acquisition capital, the investor might retain £1,500.
After 12 months:
£18,000
After 24 months:
£36,000
Once the target reserve is reached, the allocation can be reviewed.
The important part is making the reserve a deliberate portfolio objective rather than hoping spare cash accumulates naturally.
Stop Treating Every Spare Pound as Deposit Money
Portfolio growth can create pressure to keep buying.
You save £20,000.
Immediately it becomes:
“How quickly can I turn this into the deposit for another property?”
That mindset can accelerate growth.
It can also gradually remove liquidity.
Imagine an investor owns £1 million of property but has only £5,000 available in cash.
Another owns £850,000 of property with £60,000 of accessible reserves.
The first portfolio is larger.
The second may be considerably easier to hold through a difficult year.
That matters because long-term property returns frequently depend on staying invested.
Our article on the capital-growth trap explores the danger of owning an asset with an attractive long-term story that becomes financially uncomfortable to hold.
Liquidity gives an investor time.
And time can prevent temporary problems from becoming permanent losses.
Refill the Reserve After You Use It
A reserve is not a one-time target.
Suppose you build £50,000.
Then a refurbishment and extended void consume £12,000.
Your reserve is now £38,000.
That does not necessarily mean anything has gone wrong.
The reserve has performed its job.
But the portfolio should now have a plan to replenish that £12,000.
Treat reserve rebuilding as a priority before automatically directing all available surplus towards the next acquisition.
This creates a useful cycle:
Build → protect → use when necessary → rebuild.
Review the Target Every Year
A reserve calculated three years ago may no longer be appropriate.
Perhaps you have added two properties.
Perhaps mortgage payments have changed.
Perhaps rents have risen.
Perhaps service charges are higher.
Perhaps you have reduced leverage.
Perhaps a major refurbishment has recently been completed, reducing near-term maintenance risk.
Review the calculation at least periodically and whenever the portfolio changes materially.
Your reserve target should evolve with your portfolio.
Do Not Confuse Property Equity With Liquidity
An investor may own a property worth £400,000 with a £200,000 mortgage.
That represents substantial equity.
But equity cannot necessarily pay a contractor tomorrow.
Extracting it may require:
- refinancing;
- lender approval;
- valuation;
- affordability checks;
- legal work; and
- time.
Selling property takes even longer and creates significant transaction consequences.
Cash serves a different purpose.
Equity builds wealth. Cash provides flexibility.
A resilient portfolio can benefit from both.
Keep the Reserve Accessible
A portfolio emergency fund should generally prioritise liquidity over maximising return.
The purpose of this money is not to become the portfolio’s highest-performing asset.
It exists so the investor can access funds when required.
That does not mean ignoring interest completely.
It means understanding that money needed quickly should not be dependent on selling another volatile or illiquid investment first.
Your precise structure will depend on your personal, company and tax circumstances, so appropriate financial and tax advice may be required.
A Reserve Does Not Fix a Weak Property
There is an important distinction.
A cash reserve protects against temporary disruption.
It should not be used indefinitely to support an asset with fundamentally poor economics.
If a property repeatedly requires reserve money because:
- rent consistently fails to cover realistic costs;
- voids remain excessive;
- maintenance is unusually high;
- service charges undermine the return; or
- financing makes the investment structurally unviable,
the problem may be the investment rather than the size of the reserve.
This is why ongoing portfolio monitoring matters.
As our guide to hands-off property investment oversight explains, investors should continue monitoring income, costs, occupancy and asset performance even when day-to-day management has been delegated.
The reserve creates breathing room.
It should not hide poor performance.
Add the Reserve Requirement Before Buying the Next Property
One of the most useful changes an investor can make is including cash reserve requirements in the acquisition decision.
Before buying another property, ask:
If I complete this purchase, what happens to my portfolio reserve?
Suppose you currently have:
£60,000 cash reserve.
The next purchase requires:
£45,000 deposit and costs.
Completing it would leave:
£15,000.
Technically, you may be able to purchase the property.
But should you?
That is a different question.
Include the reserve position within your investment evidence before committing capital.
Residence Index UK’s guide to building a property investment evidence file before reserving provides a useful framework for separating known facts, assumptions and investment risks before money is committed.
The 12-Month Reserve Test
A simple annual review can ask:
Step 1: What are my unavoidable monthly portfolio costs?
Step 2: What would those costs look like under a higher-rate scenario?
Step 3: What realistic maintenance and compliance allowance should I include?
Step 4: How much money is already committed to tax or planned expenditure?
Step 5: What genuinely accessible cash remains?
Step 6: How many months of portfolio obligations could that cash cover?
The final number is particularly useful.
An investor might discover they have:
2.4 months of reserve.
5.7 months.
9.2 months.
14 months.
That gives liquidity a measurable role within portfolio management.
Final Thought
Property investors naturally focus on what their capital can buy.
Sometimes the stronger financial decision is deciding what not to invest.
A 12-month cash reserve can give a portfolio the capacity to absorb voids, repairs, refinancing changes and unexpected expenditure without immediately forcing the investor to sell, refinance or inject emergency personal funds.
It does not eliminate property risk.
It creates room to respond to it.
The strongest portfolio is not necessarily the one with every available pound invested.
It may be the one that can survive an uncomfortable year without changing the long-term plan.
Investors considering their next acquisition can explore the Residence Index UK property portfolio and assess each opportunity not only by expected yield and capital growth, but also by the liquidity required to hold it comfortably.
Important: Property investment involves risk. This article is for general information only and does not constitute legal, tax, mortgage or financial advice. Individual circumstances differ, and investors should obtain appropriate independent professional advice.